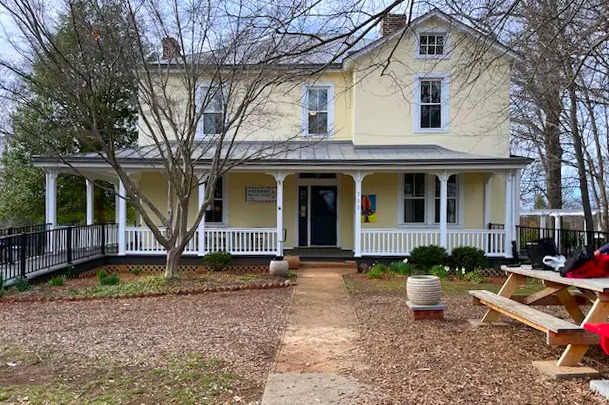
In the early 1990’s, so-called “Summit Bonds” were issued by the Church, and bought by church members, to enable the purchasing of Summit House. Whereas most Summit Bonds were redeemed (paid back) over the ensuing decades, some Summit Bonds remain on our financial documents. The remaining Summit Bonds are owned largely by the Abrahamse Fund, Cheetham Fund, and the Bristol Trust.

To better understand “the bond situation”, I, as Treasurer, spent time over the past year digging into our Church Archives to better understand the history of the Bonds, and what they mean for UUCville in 2026. I have written a ten page report reviewing my findings, and that report is available to read in its entirety below. For those who wish to read a much shorter version, below is an AI-generated summary.
A main take-away from the report is that UUCVille continues to carry $110,000 in debt related to the remaining Summit Bonds. In response, earlier this fall, the Board appointed a “Long-Term Debt Task Force” comprising myself, Donna Redmond (Chair, Finance Committee) and John Griffith (VP) with the charge of proposing solution(s) to resolve the remaining debt. The LTD Task Force expects to present its findings at the December Board meeting.
UUCVille Summit House Bond Debt: A Report from Jimmy Gorham, Treasurer, Version 5.2 | November 2026
The following is an AI-generated summary of the 2026 Summit Bond report put together by UUCville Treasurer Jimmy Gorham.
“The report by UUCVille Treasurer Jimmy Gorham provides a comprehensive investigation into the congregation’s persistent $110,000 long-term debt, which originated from bonds issued in 1992 to finance the purchase of the Summit House property. While the church successfully redeemed $420,000 of the original $530,000 debt between 1994 and 2016, repayment efforts have since stalled. Gorham argues that resolving this issue is critical for both conducting an overdue external financial audit and ensuring the success of an upcoming capital campaign.
The report identifies six historical factors that have contributed to this stagnation, most notably the entanglement of the remaining debt with the Abrahamse, Bristol, and Cheetham (ABC) Funds. These funds, which serve specific church ministries, became the holders of the remaining bonds. This has created a confusing financial cycle where the debt is incorrectly recorded as both an asset and a liability, fostering a widespread misconception among staff and congregants that the church holds a $110,000 interest-earning investment, when in reality, the interest payments are being subsidized by general operating revenue. Further complicating this are the lack of maturity dates on the original 1992 bonds, the loss of critical transaction records at a now-defunct law firm, and a failure to adjust the bond interest rates—which remain at 5.25%—to reflect modern market conditions.
To untangle this “Gordian Knot” of financial obligations, Gorham proposes a concrete, two-stage resolution. In the short term, he suggests resetting the bond interest rates to align with current market conditions, such as standard CD rates. For the medium term, he recommends a strategy to systematically retire the remaining debt over one to four years, which would allow the church to fully restore the principals to the ABC Funds and reinvest them in diverse, clearly defined vehicles that align with their original establishment documents.”